
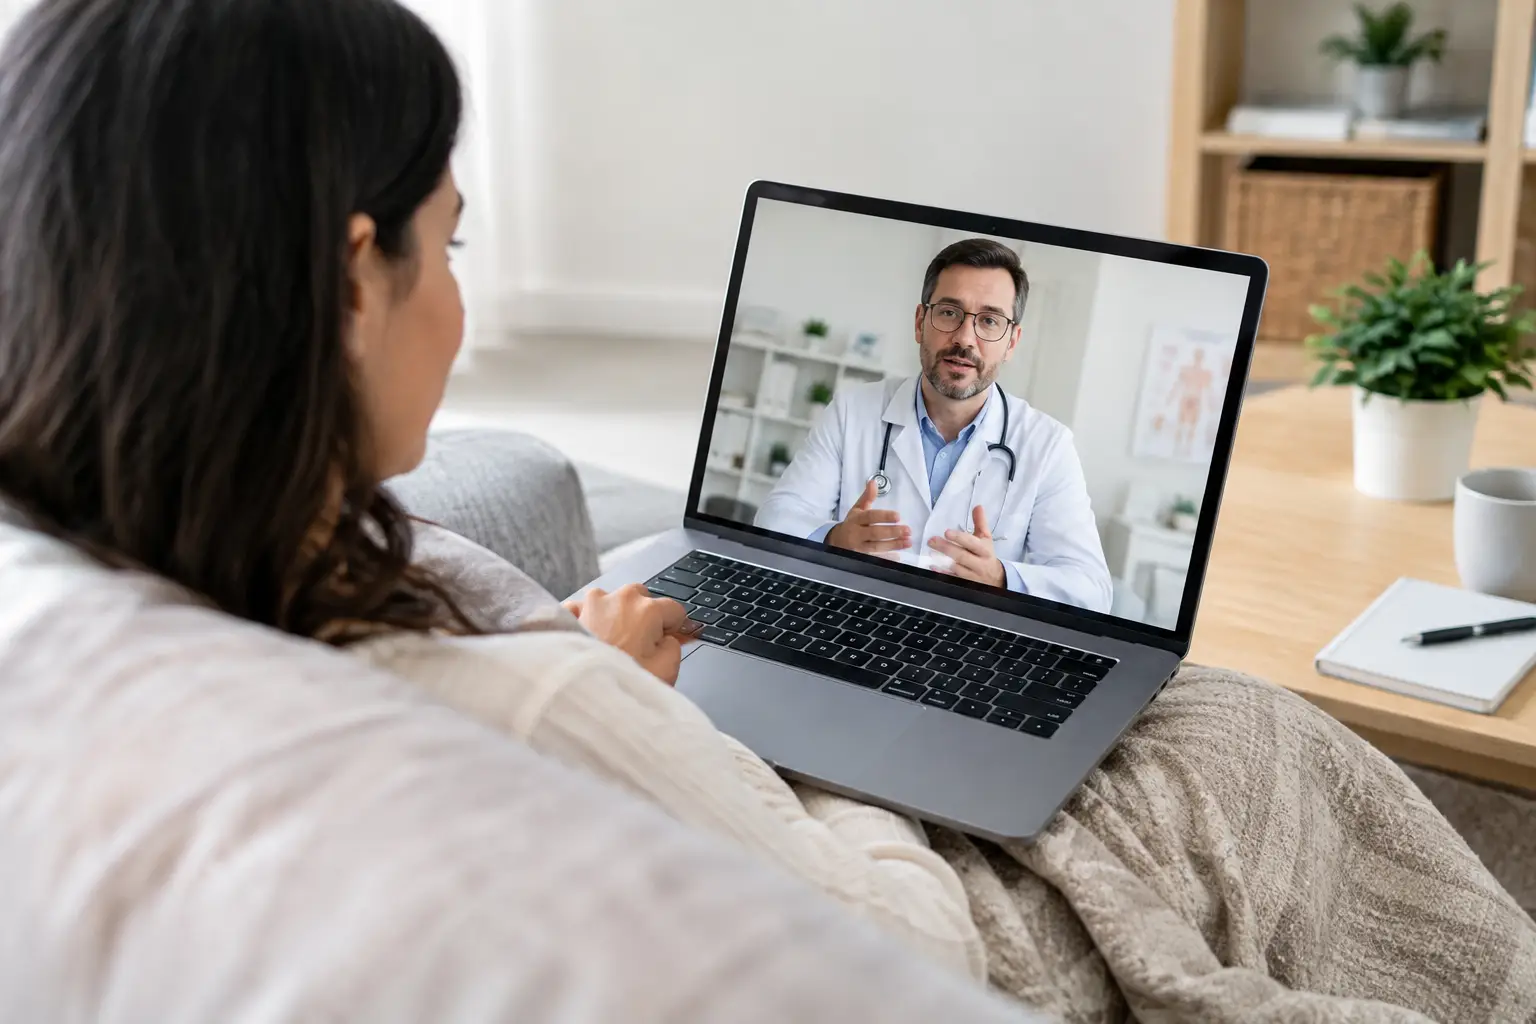
A virtual visit can save you the time it takes to drive across town, sit in a waiting room, and rearrange a workday. But before you schedule, the practical question is often: does insurance cover telehealth? For many people, the answer is yes. The more accurate answer is that coverage depends on your specific plan, the type of service you need, the clinician providing it, and the way the visit is billed.
Understanding those details before your appointment can help you avoid surprise costs and choose a care option that fits your budget and health needs.
Table of Contents
Does Insurance Cover Telehealth for Primary Care?
Many commercial health plans, Medicare, and Medicaid programs cover at least some telehealth services. Virtual primary care visits are commonly covered when they address needs that would also be appropriate in an office, such as a medication follow-up, a new non-emergency concern, chronic-condition monitoring, or preventive-care planning.
Coverage is not identical to having a free visit. Your plan may apply the same copay, deductible, or coinsurance that applies to in-person primary care. Other plans may have a separate virtual-care benefit with a different cost. If you have not met your annual deductible, you could be responsible for the full allowed amount of a covered service until that deductible is met.
The clinician’s network status matters, too. An in-network clinician generally costs less because the provider has agreed to your insurer’s contracted rates. An out-of-network telehealth appointment may receive limited coverage or no coverage at all, depending on your plan.
What Telehealth Services May Be Covered?
Telehealth is a method of receiving care, not a single service. Insurance coverage often depends more on what happens during the appointment than on whether you meet by video, phone, or in person.
Plans may cover virtual visits for routine primary care, behavioral health, dermatology concerns, sexual health, medication management, nutrition counseling, and some specialist consultations. They may also cover ongoing care for conditions such as high blood pressure, diabetes, asthma, thyroid concerns, or high cholesterol. Regular virtual check-ins can give your clinician a clearer picture of how symptoms, home readings, medications, and daily habits are changing between office visits.
Some services have more limitations. A plan may cover an initial evaluation but not an ongoing program, or it may cover a clinician visit while excluding a prescribed medication, laboratory test, wearable device, or wellness product. Services that are considered elective or not medically necessary may be excluded. Weight management, hormone care, peptide services, and certain sexual-health treatments can have plan-specific rules, even when the clinical appointment itself is covered.
Telehealth also has clinical limits. A clinician may need to see you in person for a physical examination, a test, a procedure, urgent symptoms, or findings that cannot be safely assessed on video. Virtual care works best when it is part of a thoughtful care plan, not when it delays needed hands-on evaluation.
Four Details to Check Before You Book
A five-minute call to your insurer or a review of your member portal can prevent confusion later. Ask about these four points:
- Telehealth eligibility: Confirm that your plan covers video or phone visits and whether it limits coverage to certain platforms or provider groups.
- Network status: Ask whether the clinician or telehealth practice is in network for your particular plan, not just whether the company accepts insurance generally.
- Your expected cost: Request the copay, coinsurance, deductible status, and any separate virtual-care fee that may apply.
- Service rules: Ask whether your reason for the visit, follow-up frequency, prescriptions, lab orders, or referrals require prior authorization or have coverage limits.
When you call, write down the representative’s name, the date, and any reference number for the conversation. Insurance representatives can explain benefits, but a final claim decision may still depend on the diagnosis, documentation, coding, and plan rules in effect on the date of service.
A Simple Three-Step Approach to Using Telehealth Coverage
1. Start with the care you actually need
Describe the reason for your visit clearly. Are you looking for a routine check-in, help managing an ongoing condition, a refill review, preventive guidance, or support for a new concern? This helps the care team determine whether telehealth is appropriate and whether an in-person appointment, testing, or specialist referral may also be needed.
For chronic conditions, continuity is especially valuable. A single virtual visit may address one question. Ongoing primary care can support regular blood pressure reviews, medication adjustments, preventive screening reminders, symptom tracking, and coordination when a specialist becomes involved.
2. Verify benefits using your plan information
Have your insurance card available when you contact your insurer. The member services number is usually printed on the back. You can ask, “What are my telehealth benefits for outpatient primary care?” and “What will I owe for an in-network virtual visit?”
If you are using a membership-based virtual practice, ask how its membership fee and clinical services are structured. A monthly membership may provide predictable access and ongoing support, but it is not automatically the same as an insurance-covered medical claim. Confirm whether the practice bills insurance, provides a receipt or superbill for possible reimbursement, or operates on a direct-pay basis. Do not assume your insurer will reimburse a membership fee without checking first.
3. Keep records and follow through on next steps
After the visit, review your explanation of benefits, or EOB, when it arrives. This is not a bill. It shows how the insurer processed the claim, what amount was allowed, what the plan paid, and what you may owe.
Your care may continue beyond the video appointment. You might need lab work, a screening, an in-person exam, prescription monitoring, or a specialist consultation. Ask your clinician which steps are clinically necessary, where they should be completed, and whether referrals need to be placed through your insurance plan.
When Insurance Does Not Cover a Virtual Visit
A lack of coverage does not necessarily mean telehealth is out of reach. Some patients choose self-pay care because the price is clear, appointments are available sooner, or they want an ongoing relationship rather than episodic urgent-care visits. This can be particularly useful for people whose plans have high deductibles or narrow networks.
Still, compare the full cost of care. A low monthly fee may not include prescriptions, labs, imaging, specialist visits, or emergency care. Ask what is included, what requires an additional charge, and how the clinician coordinates services outside the virtual practice.
My Healing 365 offers membership-based primary care at $99 per month, designed around regular clinician check-ins, health assessments, preventive support, and coordination across your healthcare needs. For patients considering any direct-to-consumer care membership, the key is to understand the membership terms alongside your existing insurance benefits rather than treating them as interchangeable.
Frequently Asked Questions
Does Medicare cover telehealth?
Medicare coverage for telehealth has expanded in recent years, but rules can change and may vary by service, provider, location, and Medicare plan type. Original Medicare and Medicare Advantage plans can have different details. Check your current plan materials or call your plan before scheduling.
Is a phone appointment covered the same as a video visit?
Not always. Some plans cover audio-only visits for certain services or circumstances, while others require real-time video. Ask specifically about telephone-only appointments if video access is a concern.
Can telehealth providers prescribe medication?
Often, yes, when it is clinically appropriate and permitted under applicable laws and plan rules. Coverage for the prescription is separate from coverage for the visit. Your formulary, pharmacy network, prior authorization requirements, and deductible can all affect what you pay.
Can I use HSA or FSA funds for telehealth?
Many qualified medical expenses, including eligible telehealth services, may be paid with HSA or FSA funds. Eligibility depends on the expense and the rules of your account. Review your plan guidance and keep receipts.
The best telehealth experience starts with clarity: know what your plan covers, know what your care team can manage virtually, and choose a model that gives you the level of follow-up your health deserves.